Finding top local mortgage brokers in your area step by step
Why Work with Local Mortgage Brokers Near Me?
When shopping for a home financing strategy, many buyers default to the big bank down the street out of habit. However, actively searching for local mortgage brokers near me opens up an expansive network of wholesale pricing, competitive interest rates, and highly personalized customer service. Unlike retail bank loan officers who are restricted to a limited menu of proprietary products, independent local mortgage brokers function as your dedicated personal loan shopper.
Because independent brokers maintain direct relationships with multiple wholesale lenders, they possess the structural flexibility to tailor a financing package to your specific situation, rather than attempting to force your unique financial profile into a rigid, one-size-fits-all box. Furthermore, direct, ongoing communication with your local broker ensures you are never routed to an endless customer-service call queue or shuffled between indifferent corporate departments.
The Benefits of Working with a Local Mortgage Broker
Working with an independent loan officer through an established local brokerage gives home buyers access to competitive wholesale rates that are rarely available directly to retail banking customers. Wholesalers operate with reduced overhead costs, passing those savings along to borrowers through lowered interest rates and discounted loan fees.
Independent brokers handle all the heavy lifting and administrative labor: gathering your financial documentation, analyzing pricing models across competing institutions, negotiating favorable loan terms, and tracking processing timelines.
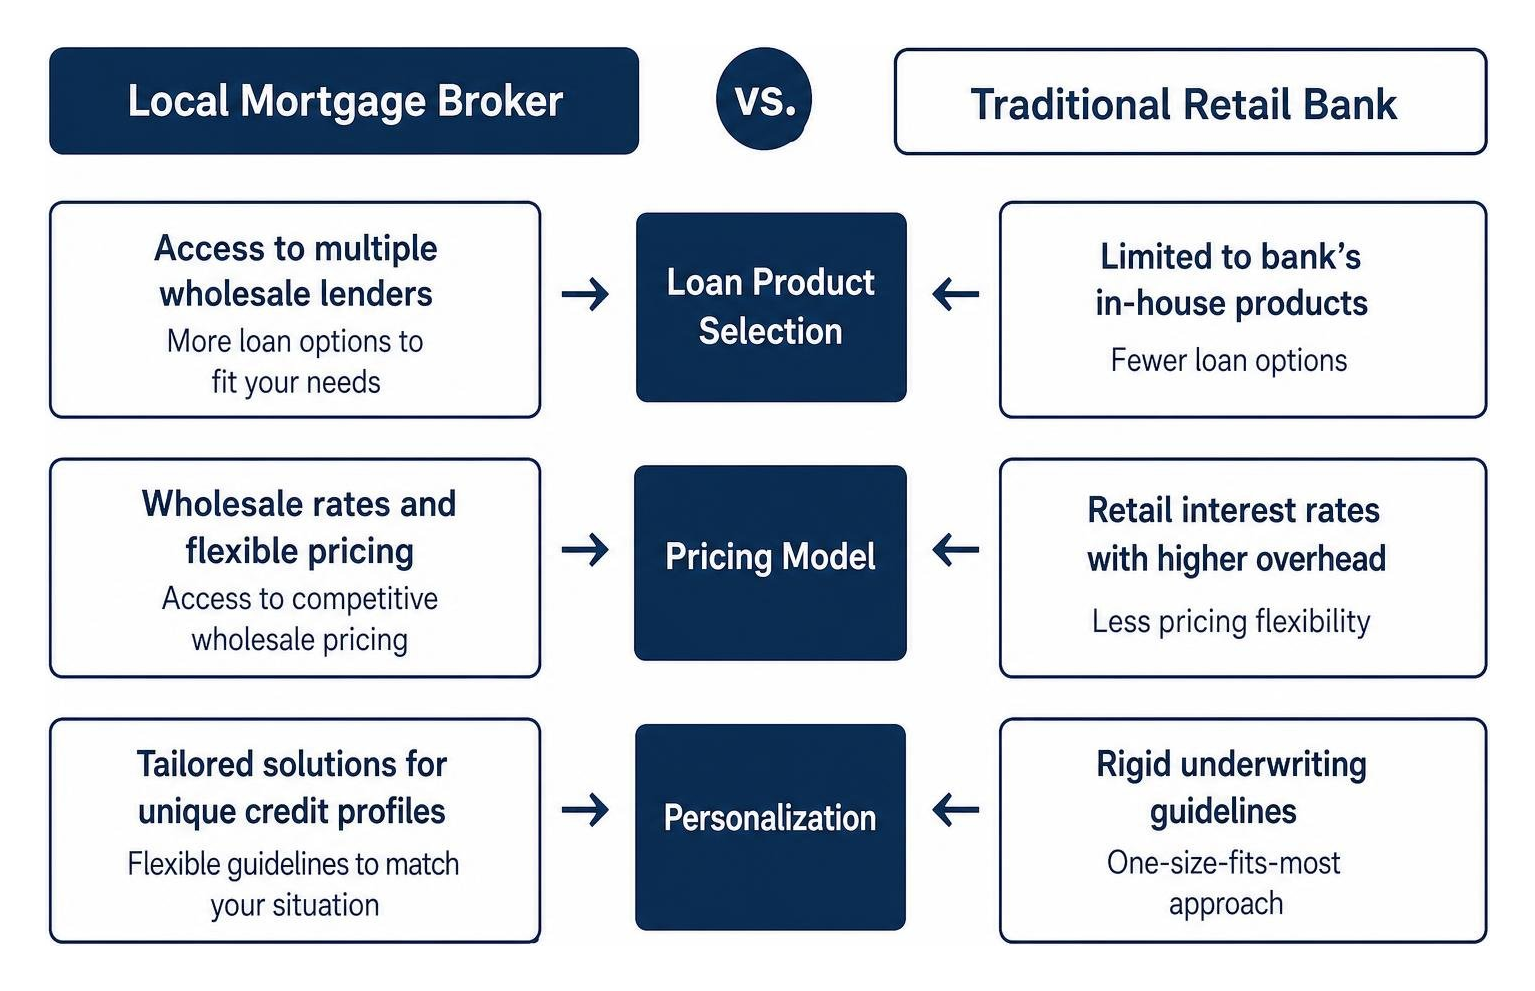
| Feature / Advantage | Local Mortgage Broker | Traditional Retail Bank |
|---|---|---|
| Loan Product Selection | Access to multiple wholesale lenders | Limited to bank's in-house products |
| Pricing Model | Wholesale rates and flexible pricing | Retail interest rates with higher overhead |
| Personalization | Tailored solutions for unique credit profiles | Rigid underwriting guidelines |
| Communication | Direct line to broker and dedicated team | Call centers and automated status updates |
| Local Knowledge | Deep familiarity with regional real estate | Generalized national rules |
The Power of Local Market Knowledge
Real estate is inherently hyper-local, and mortgage financing is deeply tied to regional economic conditions. A broker rooted in your community possesses invaluable insight into municipal property tax structures, specific regional appraisal nuances, evolving homeowners insurance market trends, and practical title company turn times.
For instance, if you are working through complex regional property guidelines or competitive multiple-offer real estate markets, having an advisor who understands local turn times ensures your offer remains highly attractive to sellers. Picking the right loan officer can be the difference between a smooth closing and a delayed one. Here is how to find the right loan officer. Furthermore, if you are questioning broader market dynamics—such as whether should you wait to buy a home in florida —a knowledgeable local broker offers real-time regional market data to help you accurately evaluate current mortgage rates against property appreciation trends.
Step-by-Step Guide to Finding and Vetting Brokers
Finding the right mortgage broker requires a bit of deliberate research, but taking a systematic approach ensures you partner with an ethical, highly skilled professional who prioritizes your financial interests.
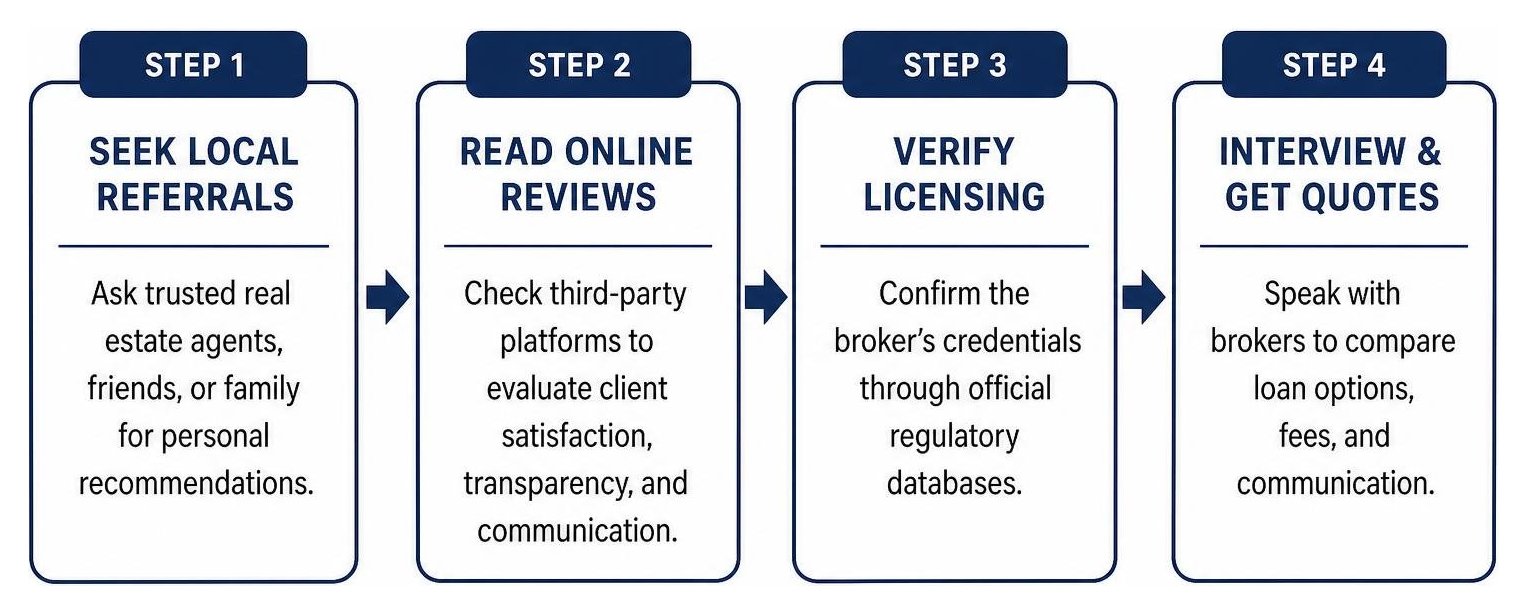
- Seek Local Referrals: Begin by asking trusted local real estate agents, financial planners, friends, or family members for personal recommendations based on recent, successful closing experiences.
- Read Online Client Testimonials: Carefully review independent third-party platforms to evaluate past client satisfaction, fee transparency, problem-solving ability, and overall communication style.
- Verify Official Licensing: Confirm professional credentials and active standing through official state and federal regulatory licensing databases.
- Schedule Initial Consultations: Speak directly with top candidate brokers to evaluate their available wholesale loan products, fee structures, response times, and general communication habits.
Verifying NMLS Credentials and Licensing for Local Mortgage Brokers Near Me
Before sharing sensitive financial documents or personal identifying information, always verify a broker's active professional standing. Every legitimate mortgage loan originator in the United States must maintain an active, valid record on the NMLS Consumer Access database.
Checking the NMLS registry allows home buyers to review state licensing statuses, official employment history, disciplinary records, and any past regulatory compliance actions. A licensed broker has to follow federal and state lending rules, and you can check that license on NMLS Consumer Access.
Key Questions to Ask Local Mortgage Brokers Near Me Before Hiring
When interviewing potential mortgage brokers, ask targeted questions designed to gauge their operational transparency, industry experience, and customer commitment:
- Which wholesale lenders are in your active network, and why do you choose to partner with them?
- What are your current average turn times from initial application submission to clear-to-close approval?
- How are broker fees and commissions handled for my specific loan scenario?
- Can you provide recent client references or direct me to verified client reviews?
- How quickly can you issue an official Loan Estimate so I can get a quote and compare true loan costs?
- What specific loan structuring strategies do you recommend for my target purchase price and credit profile?
Loan Programs, Fees, and Getting Pre-Approved

A top-tier local mortgage broker does far more than simply quote an interest rate; they act as a strategic advisor who aligns your immediate purchasing power with long-term financial stability across specialized loan programs tailored to your budget.
First-Time Homebuyer Programs and Rate Comparison
If you are purchasing your first property, local brokers excel at identifying valuable down payment assistance grants and flexible government-backed home financing programs:
- FHA Loans: Insured by the Federal Housing Administration, these loans offer flexible credit guidelines and a smaller down payment.
- VA Loans: Guaranteed by the Department of Veterans Affairs, offering flexible down payment options and competitive rates for eligible service members, veterans, and surviving spouses.
- USDA Loans: Designed to spur rural development, with flexible down payment options for eligible homes in qualifying rural areas.
- Conventional Loans: Highly adaptable loan products conforming to Fannie Mae or Freddie Mac guidelines, offering flexible private mortgage insurance terms for borrowers with strong credit scores.
Understanding these diverse programs is vital when preparing to buy a home. Your broker will explain critical loan mechanics, such as what credit score do you need for a mortgage to qualify for top-tier interest rates, and help you evaluate what is pmi mortgage insurance and how it impacts your total monthly housing cost across different down payment levels.
Understanding Broker Fees, Commissions, and Pre-Approval
Understanding how mortgage brokers are compensated is straightforward and transparent:
- Lender-Paid Compensation: The selected wholesale lender pays the broker firm a standardized percentage upon loan closing. This is the most common arrangement and requires no direct, out-of-pocket payment from the home buyer at closing.
- Borrower-Paid Compensation: In certain specialized loan scenarios, the borrower pays the broker fee directly as a line item in their overall closing costs. Federal regulations dictate that mortgage brokers cannot collect compensation from both the lender and the borrower on the exact same loan transaction.
All projected settlement costs and broker fees must be fully disclosed upfront within official disclosures standardized by the Consumer Financial Protection Bureau on page 2 of your standardized Loan Estimate document.
Securing a robust pre-approval early in your home search provides absolute clarity on your true purchasing power. You can submit your preliminary financial documents to begin your formal Pre Approval, utilize an interactive online mortgage calculator to test various purchase price scenarios, and proactively address any potential trouble getting pre-approved long before placing an offer on a house. Once under contract, your dedicated broker will advise you on optimal market timing regarding when to lock your mortgage interest rate.
Frequently Asked Questions About Local Mortgage Brokers
How are local mortgage brokers paid?
Mortgage brokers are paid either through lender-paid compensation or direct borrower-paid fees, but never both on the same transaction. The fee structure is locked in advance and clearly disclosed on federal regulatory disclosures like the Loan Estimate, ensuring brokers cannot arbitrarily inflate interest rates or tack on unearned hidden margins for personal profit.
How do local mortgage broker costs compare to traditional banks?
Because independent mortgage brokers access wholesale lending channels directly, their total rate-and-fee packages are frequently lower than retail bank offerings. Independent brokers operate without the massive corporate overhead, physical branch upkeep, and extensive management layers of commercial banks, allowing wholesale lenders to pass these operational savings directly to borrowers via competitive interest rates and reduced origination fees.
How quickly can a local mortgage broker close a home loan?
A good local broker can often close faster than a big bank, because we are not stuck in one lender's queue. Their direct access to dedicated wholesale processing teams and localized appraisal management companies streamlines underwriting, giving you a distinct competitive advantage when submitting an offer on a tight contract deadline.
Conclusion
Finding and partnering with the right local mortgage broker is one of the single most effective strategies to streamline your home purchase or refinancing process. By aligning with an independent expert who deeply understands your local real estate market, shops multiple wholesale lenders, and provides transparent financial disclosures, you establish a firm foundation for long-term financial success.
At Home Loan Advisors, our education-driven approach gives you the personalized support, competitive wholesale rate choices, and crystal-clear communication you deserve—from your initial pre-approval strategy session all the way to a smooth, stress-free closing. Ready to explore your ideal home loan options? Take the next confident step today and contact our experienced team at Home Loan Advisors!